Payday Loan Rollovers: Mathematical Compounding & Debt Trap Prevention
How does rolling over a small $400 emergency cash advance across twelve bi-weekly pay cycles result in paying over $1,400 in finance charges while leaving the entire original balance unpaid? The single most dangerous structural trap in short-term small-dollar lending is the loan rollover (also known as a renewal or extension). When a borrower pays a non-refundable renewal fee simply to extend their payment deadline by two weeks, zero dollars reduce the loan principal. This guide analyzes the compounding mathematics of repeated renewals, state statutory rollover bans, and proven strategic exit ramps to escape chronic debt cycles.
1. The Anatomy of a Loan Rollover
In standard deferred presentment transactions, loan maturity coincides with the borrower's upcoming payday. When the borrower lacks sufficient funds to surrender the entire principal plus fee, lenders offer a rollover:
- Pay the Finance Fee Only: The borrower pays only the non-refundable finance charge (e.g., $15 per $100 borrowed). On a $500 loan, the borrower hands over $75 in cash or authorizes an electronic debit for $75.
- Extend the Due Date: The lender extends the loan maturity date by another 14 days (or one full pay cycle).
- Zero Principal Reduction: The borrower still owes the full $500 principal. In two weeks, the borrower faces the exact same dilemma—either pay $575 in full, or pay another $75 fee to roll the debt over again.
According to CFPB supervisory findings, over 80% of payday loan volume is generated by borrowers locked in continuous rollover cycles, with half of all loans belonging to loan sequences of 10 or more transactions.
2. The Mathematical Escalation of Chronic Rollovers
To grasp how rapidly renewal fees outstrip the original cash borrowed, examine the cumulative cost progression of an initial $400 principal advance ($60 fee per 14-day cycle):
| Rollover Sequence | Time Elapsed | Cumulative Fees Paid | Principal Remaining | Cumulative Fee % on $400 |
|---|---|---|---|---|
| Initial Loan | Day 14 | $60.00 | $400.00 | 15.00% |
| Rollover #2 | Day 28 (1 Month) | $120.00 | $400.00 | 30.00% |
| Rollover #4 | Day 56 (2 Months) | $240.00 | $400.00 | 60.00% |
| Rollover #7 | Day 98 (3.5 Months) | $420.00 (Fees exceed principal!) | $400.00 | 105.00% |
| Rollover #12 | Day 168 (6 Months) | $720.00 | $400.00 | 180.00% |
| Rollover #26 | Day 364 (1 Year) | $1,560.00 | $400.00 Still Owed | 390.00% |
By Month 3.5 (Rollover #7), the borrower has paid more in non-refundable renewal fees ($420) than the original $400 cash they received—yet they still owe the exact same $400. Over an entire year, the borrower spends $1,960 in total cash to service a $400 temporary shortfall.
3. State Legislative Countermeasures: Rollover Bans & Cooling-Off Windows
Because empirical data demonstrates that rollovers lead directly to borrower insolvency, progressive state statutes have enacted strict legislative prohibitions:
- Complete Rollover Bans: Numerous states (including California under Financial Code § 23037, Florida, and Michigan) legally prohibit lenders from rolling over a payday advance. The loan must be repaid in full before a new transaction can be originated.
- Mandatory Cooling-Off Periods: States like Ohio, Washington, and Virginia mandate cooling-off periods (typically 24 hours to 30 days) after a borrower has taken consecutive advances or reached statutory annual borrowing limits (e.g., maximum 8 loans in a 12-month period in Washington).
- Anti-Evasion Databases: Lenders are legally prohibited from evading rollover bans by coordinating with affiliated stores or brokers to "repay" one loan with another. State real-time databases track borrower SSNs across all licensed institutions.
4. Five Strategic Exit Ramps to Break the Cycle
If you currently find yourself trapped in a continuous rollover pattern, execute one of these five proven exit strategies:
Proven Strategies to Escape Chronic Rollovers:
- Request a Zero-Fee Extended Payment Plan (EPP): Before paying your next renewal fee, contact the lender in writing and demand an EPP. Under trade standards and state law, this freezes the debt and spreads it across 4 zero-interest installments.
- Refinance with a Credit Union PAL Loan: Federal credit unions originate Payday Alternative Loans (PALs) capped at 28% APR with 6-month terms. Borrowing $500 on a PAL loan costs approximately $45 in total interest and allows you to wipe out the payday advance permanently.
- Negotiate a Lump-Sum Payoff Settlement: If the loan has rolled over repeatedly, speak with a branch manager or compliance officer. Inform them that the cumulative fees paid already exceed the principal and request to settle the debt in full for a nominal final payment.
- Employer Earned Wage Access (EWA): Inquire whether your employer utilizes an integrated EWA platform (such as DailyPay or Even) that permits accessing already-earned wages for a nominal $1 to $3 transfer fee.
- Non-Profit Credit Counseling: Enroll in a Debt Management Plan through an accredited NFCC agency, which contacts lenders to negotiate fee waivers and structured repayment terms.
5. Rebuilding Cash Flow Independence
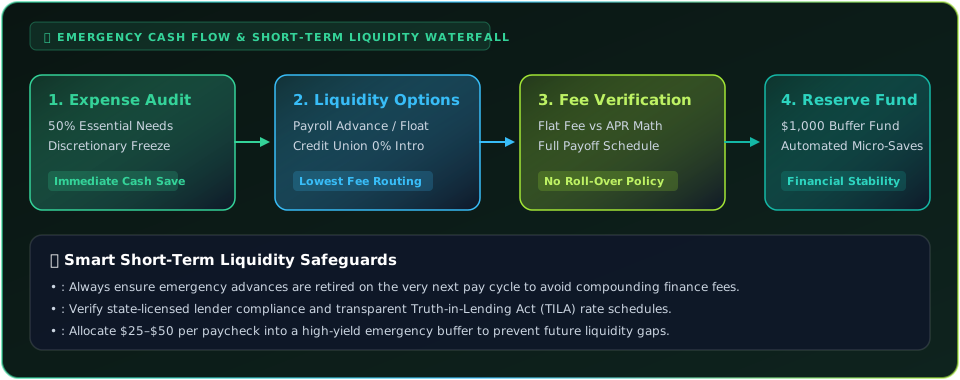
Once you successfully liquidate a short-term advance, direct the $60 to $150 you were previously surrendering in bi-weekly rollover fees into a dedicated, high-yield starter savings account. Within 90 to 120 days, you will accumulate a self-funded $500 to $1,000 emergency buffer, permanently insulating your household from ever needing short-term high-cost credit again.
Cash 4 You Live Editorial & Consumer Advocacy Board
Our financial literacy researchers and regulatory analysts publish independent guides on Truth in Lending APR compliance, credit union PAL alternatives, and state usury statutes.